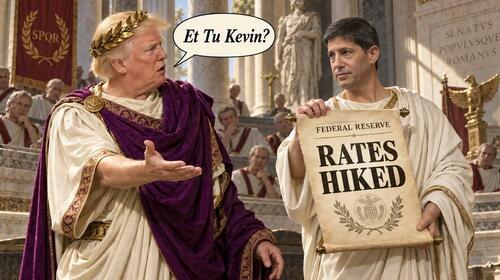
Fed Delivers 25-Basis-Point Hike, Signals Further Tightening Ahead
The US dollar index (DXY00) surged to a 1.5-month high on Wednesday, closing 0.64% higher on the session. The greenback's rally was driven by a combination of stronger-than-anticipated US economic data and a hawkish Federal Reserve decision that left forex traders and institutional desks bracing for continued dollar strength in the coming weeks.
The FOMC, in a move widely anticipated by markets, raised the federal funds target range by 25 basis points to 3.75%–4.00%. In its statement, the committee noted that the increase would support a "timelier" return to its 2% inflation target. The statement also highlighted that while uncertainty persists—partly due to geopolitical developments—domestic spending has remained resilient, productivity growth is solid, and capital investment is robust.
The more significant signal came from the updated dot plot. The median year-end projection for the federal funds rate now sits at 4.125%, a notable jump from the 3.750% median recorded in June. Sixteen of the eighteen FOMC participants indicated they expect at least one additional rate increase before the end of 2026. The committee also nudged its 2026 GDP forecast upward to 2.3% from 2.2% in the June projection and lifted its 2026 core inflation estimate to 3.4%, up from the prior 3.3%.
Fed Chair Warsh framed the decision as a step to "remove a dose of accommodation," emphasizing that inflation remains too elevated for too long, with a significant number of price categories still climbing at rates above 3%. Traders are now pricing in a 57% probability of another 25-basis-point hike at the FOMC's next meeting scheduled for October 27–28.
US Data Mix Fuels Dollar Gains, Housing Weakness Offers a Caveat
Ahead of the Fed's decision, a series of US economic indicators reinforced the case for tighter policy. August retail sales jumped 1.2% month-over-month, well above the 0.8% consensus and marking the largest monthly gain in five months. Excluding auto sales, the figure came in at 1.4% versus an expected 0.6%.
The August import price index, excluding petroleum, rose 0.8% month-over-month, nearly triple the 0.3% that analysts had forecast, underscoring persistent cost pressures in the goods supply chain.
On the downside for the housing sector, the September NAHB Housing Market Index dropped three points to 32, matching a 3.75-year low and falling short of the 34 level that economists had anticipated. For forex brokers and their retail clients, this mix of strong consumption data alongside a weakening housing sector paints a complex picture for US growth in the second half of 2026.
EUR/USD and USD/JPY Reactions: Euro and Yen Under Pressure
The euro came under direct selling pressure, with EUR/USD slipping to a 1.5-month low and finishing 0.68% lower. The dollar's post-Fed strength was the primary driver, though the euro found modest comfort in Eurozone July industrial production, which declined just 0.1% month-over-month versus the 0.2% drop expected. Additionally, a 3% drop in crude oil prices on the day eased energy-cost concerns for the oil-importing Eurozone economy. Markets are currently discounting a 52% chance of a 25-basis-point ECB rate hike at the central bank's October 29 policy meeting.
The Japanese yen faced similar headwinds, with USD/JPY climbing 0.66% and the currency touching a one-week low. Beyond the Fed's hawkish pivot, the yen was weighed down by a disappointing July core machine orders print of -3.7% month-over-month, far weaker than the -1.2% consensus. The currency also absorbed spillover pressure from reports that the Japanese government is weighing a new defense spending target of 3.5% of GDP, a move that could swell government bond issuance and further weaken the yen.
Offsetting some of that weakness, Japan's August trade figures beat expectations: exports rose 19.3% year-over-year (against 18.4% expected), while imports surged 28.0% year-over-year (versus 26.3% forecast), the largest import increase in 3.75 years. The 3% decline in crude oil prices also provided a tailwind, given that Japan imports more than 90% of its energy needs.
Looking ahead, the yen has a potential catalyst in Friday's Bank of Japan policy meeting, where markets are pricing a 100% probability of a 25-basis-point rate hike. The government has signaled support for the move to defend the yen and contain imported inflation. Additionally, the recent coordinated US-Japan FX intervention and the risk of follow-on action if the yen stays soft continue to underpin the currency. Speculation also persists around the Government Pension Investment Fund (GPIF), which manages $2.1 trillion in assets. Last Tuesday, the health minister overseeing the GPIF indicated the fund is still deliberating whether to review its asset allocation—a possible signal of increased domestic bond buying following the 10-year JGB yield's jump to a 30-year high.
Precious Metals Rally Before Fed-Driven Reversal; Positioning Stays Bullish
Precious metals enjoyed a strong intraday session on Wednesday. December COMEX gold (GCZ26) closed up 54.70 dollars, or 1.26%, while December COMEX silver (SIZ26) added 1.063 dollars, a 1.66% gain. The rally was supported by the 3% drop in WTI crude oil, which tempered inflation expectations and raised the prospect of more dovish policy from central banks, alongside lower global bond yields.
However, the tone shifted sharply in post-market hours. After the Fed's rate decision and hawkish guidance, gold briefly plunged more than 75 dollars per ounce as the dollar's surge to its 1.5-month high exerted immediate downside pressure on the metal.
Underlying positioning remains constructive. Long holdings in gold exchange-traded funds climbed to a 6.5-month high on the day, while long positions in silver ETFs reached a 5.5-month high on August 25. Central bank demand continues to underpin the market: China's People's Bank of Report (PBOC) added 650,000 troy ounces of bullion to its reserves in August, bringing the total to 76.73 million troy ounces. That marked the largest monthly increase in three years and the twenty-second consecutive month of accumulation.
